Deal activity in Saudi Arabia has expanded sharply, creating a backdrop for more disciplined conversations about mining transactions, licence transfers, and platform-building. Invest Riyadh’s Mega-Deal Tracker says total announced transaction value exceeded $85 billion in 2024, up from $28.0 billion in 2020, and describes Saudi Arabia as ranking among the top 10 global M&A markets and the largest deal market in the Middle East by a wide margin. The same dashboard notes PIF-linked transactions represented 43–48% of total deal value, highlighting how sovereign capital can shape where deal flow concentrates. For mining stakeholders, that matters because the Kingdom’s deal ecosystem is not only corporate M&A. It also includes concessions, joint ventures, and strategic partnerships that can change who controls operating rights and development timelines.
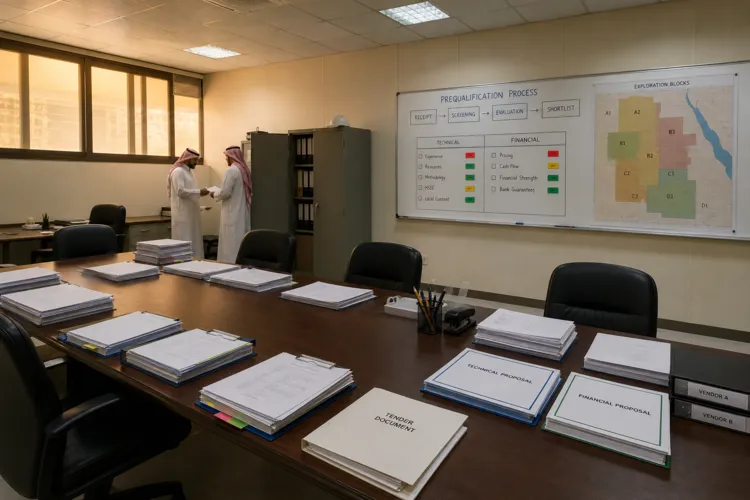
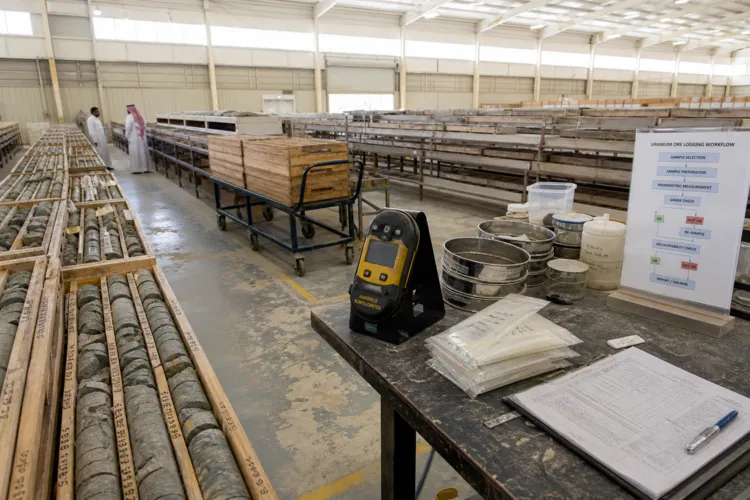
In mining specifically, licence awards are becoming a core part of “deal flow” because they allocate future production optionality and can later drive joint ventures or consolidation. S&P Global reports that in Saudi Arabia’s ninth licensing round, the Kingdom awarded 172 mining sites across three mineral-rich belts, attracting about 671 million Saudi Arabian riyals (US$179 million) in pledged investments. S&P also says the 10th round will cover 13,000 sq km and will be announced at the Future Minerals Forum in Riyadh on Jan. 13–15, 2026. Alongside licensing, exploration spending is rising. S&P states Saudi Arabia’s minesite exploration budget increased to $146 million in 2025 from $21 million in 2022, with 72% allocated to gold and 23% to copper, signaling which commodities may anchor future project-level transactions.
From Greenfield Preference to More M&A-Style Entry
Invest Riyadh’s analysis of greenfield versus M&A explains why transaction structures in Saudi Arabia can look different from older mining jurisdictions. It states that Saudi Arabia has historically been dominated by greenfield investment, and that the government explicitly prefers greenfield investment because it creates new productive capacity, new jobs, and new technology transfer. The same analysis adds that incentives are “heavily weighted” toward new construction, citing MODON land grants, SIDF loans, customs exemptions, and sector subsidies. It also notes the universe of acquisition-ready targets at $50+ million enterprise value is small, and that many mid-market Saudi companies are family-dominated and not structured for sale. Even so, Invest Riyadh says this pattern is shifting as the privatization pipeline creates M&A opportunities and the corporate sector matures, which can expand the practical options for investors beyond pure greenfield entry.
Mining-sector growth signals can add momentum to both licence transfers and selective acquisitions. Arab News reports that in 2025 the number of exploitation licenses soared by 220% and total investments climbed to SR44 billion ($11.7 billion). The same report says Saudi Arabia improved in the global Mining Investment Attractiveness Index, rising from 104th place to 10th. These indicators can change how buyers and sellers price optionality around permitted ground, development-ready licenses, and operating teams. They also raise execution expectations. S&P flags challenges from resource constraints, workforce development, and heightened ESG expectations, suggesting that deals may increasingly value operational capability and compliance readiness, not only geological upside.
Strategy signals from mining-focused deal commentary also emphasize domestic buildout over headline-grabbing overseas acquisitions. The Saudi Mining M&A 2026 guide states that Saudi Arabia has said it has identified $2.5 trillion of metals and minerals inside the country, while also noting that foreign investment has been slow to arrive. It argues that this gap increases the importance of partnerships, joint ventures, and selective acquisitions that accelerate execution inside the Kingdom, and references Bloomberg reporting that a Saudi mining investment vehicle intended for foreign mining assets is shifting away from global acquisitions. In that context, the guide points to partnerships and selective acquisitions that support Ma’aden’s stated $110 billion, decade-long shift toward vertically integrated mining, processing, and manufacturing inside Saudi Arabia. For investors tracking mining mergers and acquisitions in Saudi Arabia, the message is clear: licences, local buildout, and execution capacity increasingly define what “deal value” means.
What signals are shaping mining mergers and acquisitions in Saudi Arabia today?
How big was Saudi Arabia’s ninth mining licensing round?
What do the latest exploration budget figures show?
Why do many investors still enter via greenfield projects instead of acquisitions?
What happened to exploitation licenses and mining investment in 2025?