For mining joint ventures and other capital-heavy projects, the biggest compliance question is often not “Which rate applies?” but “Which regime applies to which owners?” In Saudi Arabia, Zakat and corporate income tax are both administered by the Zakat, Tax and Customs Authority (ZATCA). The two systems are not interchangeable. Sources emphasize that ownership structure is the starting point, and that a single Saudi-registered company can have obligations under both regimes at the same time when ownership is mixed. This is why mixed-ownership joint ventures can feel complex even when the rules are clear.
Zakat applies to qualifying Saudi and GCC-owned persons and entities, and it is described as a legally enforceable fiscal duty for businesses with Saudi or GCC ownership. Multiple sources state a 2.5% Zakat rate, charged on a company’s Zakat base rather than its profit. The Zakat base is presented as a net worth or adjusted net assets concept, with one source describing it broadly as net equity adjusted for certain items. This wealth-based approach contrasts with corporate income tax, which focuses on net taxable income over a fiscal period and is calculated under Saudi tax law with adjustments.
How Mixed Ownership Splits Zakat and Corporate Income Tax in Joint Ventures
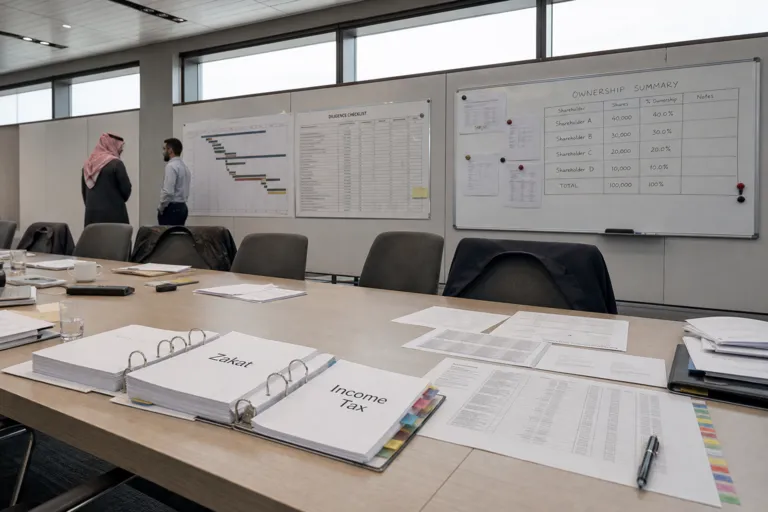
Mixed ownership is the key joint venture issue for Saudi mining structures because ZATCA does not treat the company as choosing one system. One source illustrates the mechanics using a 60% Saudi-owned and 40% foreign-owned company. In that scenario, the business calculates and files both: Zakat on the portion of the Zakat base attributable to Saudi shareholders, and corporate income tax on the portion of taxable income attributable to foreign shareholders. GCC nationals are treated identically to Saudi nationals for Zakat purposes, and this classification is applied at the shareholder level. Several sources also stress that ZATCA can trace ownership through to a foreign parent, applying corporate income tax to the foreign share.
Corporate income tax is described as applying to foreign-owned entities (non-GCC) operating in Saudi Arabia at a rate of 20% on net taxable income derived from sources within the Kingdom. PwC’s summary similarly states that the rate of income tax is 20% of net adjusted profits, and repeats that the portion attributable to non-Saudi or non-GCC interests is subject to income tax, while the Saudi share goes into the basis on which Zakat is assessed. Sources also note that withholding tax (WHT) exists, with PwC giving a range of 5% to 20% depending on payment type, and another guide stating WHT must be remitted within 10 days of the month following the payment.
For teams searching for practical clarity on zakat and corporate tax mining companies Saudi Arabia, the core takeaway is that compliance follows ownership and calculation base. Zakat is assessed at 2.5% on the Zakat base tied to Saudi and GCC shareholders, while corporate income tax is assessed at 20% on net adjusted profits or net taxable income tied to non-GCC shareholders. Because ZATCA administers both systems under one authority, mixed-ownership mining joint ventures should plan for parallel computations, aligned documentation, and timely filing through ZATCA’s portal so that each shareholder slice is treated under the correct regime.
Do Saudi mining joint ventures ever pay both Zakat and corporate income tax?
What Zakat rate applies to Saudi- and GCC-owned business interests?
What corporate income tax rate applies to foreign (non-GCC) ownership in Saudi Arabia?
Are GCC shareholders treated differently from Saudi shareholders for Zakat purposes?
What is the timing rule mentioned for withholding tax remittance?