Ferroalloys are essential inputs for steel and other metallurgical applications. They help deliver strength, hardness, corrosion resistance, machinability, and production-process control. Verified Market Reports describes the global ferroalloys market at USD 50.3 Billion in 2024, with a forecast of USD 86.7 Billion by 2032 and an anticipated 8.4% CAGR for 2025–2032. That global context matters when discussing ferroalloy production in Saudi Arabia because steelmaking activity, ore quality, electricity availability, environmental regulation, and logistics all shape where capacity can scale and how competitive it can be.
At the raw-material level, manganese ore and chromite are repeatedly flagged as vital feedstocks across the sources. Verified Market Reports notes that ferroalloys are largely composed of iron combined with elements such as chromium, manganese, and silicon. It also highlights that control over these raw materials is concentrated among a handful of countries, notably South Africa, China, India, and Russia, which influence global pricing and supply stability. For Saudi Arabia, that concentration frames the opportunity: when a steel industry grows, access to consistent manganese- and chromite-linked supply becomes a strategic lever, not just a procurement task.
Why Manganese and Chromite Matter Most for Steel-Linked Demand
Manganese-based ferroalloys track steel demand because they serve as deoxidizers and alloying agents in steelmaking. Verified Market Reports values the global ferro manganese market at 16.5 billion USD (2025), with a forecast of 24.5 billion USD by 2034 and a 5.5% CAGR for 2026–2034. The same publisher values the global silico manganese market at USD 15.25 billion in 2024, estimated to reach USD 23.56 billion by 2033, also at a 5.5% CAGR for 2026–2033. Its regional framing explicitly includes the Middle East, listing Saudi Arabia alongside the UAE, Kuwait, and Qatar, which supports discussing Saudi Arabia as part of an addressable regional market rather than an isolated endpoint.
Chromite-based ferrochrome ties even more directly to stainless steel. Verified Market Reports states that stainless steel demand accounts for approximately 70% of ferrochrome consumption, and it describes ferrochrome as a foundational raw material for stainless steel production that relies on chromite ore extraction and high-temperature smelting. Its regional lens also includes the Middle East, with Saudi Arabia listed among the countries in scope. For Saudi-focused planning, the implication is clear: the closer local steel strategies move toward stainless or corrosion-resistant grades, the more important chromite-linked supply reliability and compliant production routes become.
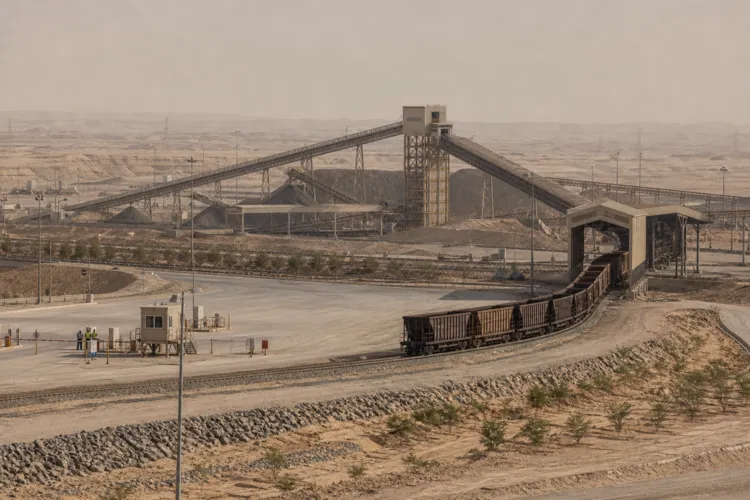
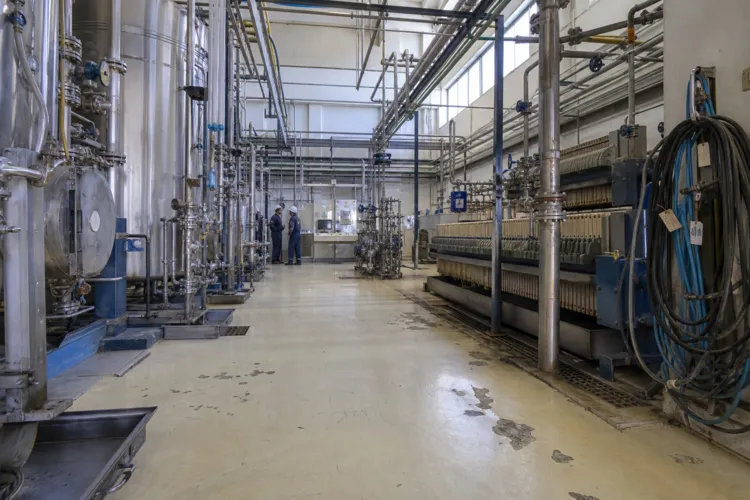
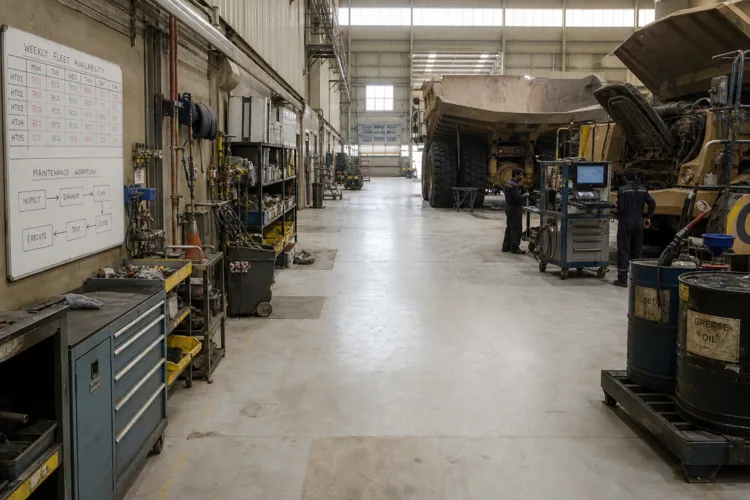
Across the sources, the direction of travel is toward efficiency, traceability, and lower-emissions operations. 360iResearch describes a landscape shaped by industrial decarbonization, energy-market volatility, trade-policy changes, and resilience priorities. It adds that smelters and downstream users are emphasizing energy efficiency, renewable electricity, recovery of by-products, emissions measurement, and traceable sourcing. It also notes that artificial intelligence can support predictive maintenance, furnace-condition monitoring, raw-material blending, energy optimization, and quality-control automation. For ferroalloy production Saudi Arabia, these themes define how local manganese and chromite link to steel: not only through ore and furnaces, but through data, energy exposure management, and the ability to meet evolving carbon and environmental requirements.
What role do ferroalloys play in steelmaking tied to Saudi Arabia’s industrial growth?
Which raw materials are most often linked to ferroalloy supply security?
How large is the global ferroalloys market in the sources?
Why is ferrochrome demand closely connected to stainless steel?
What operational shifts could shape ferroalloy production in Saudi Arabia over time?